The Three Decisions That Determine Whether Public Realm Creates or Destroys Value
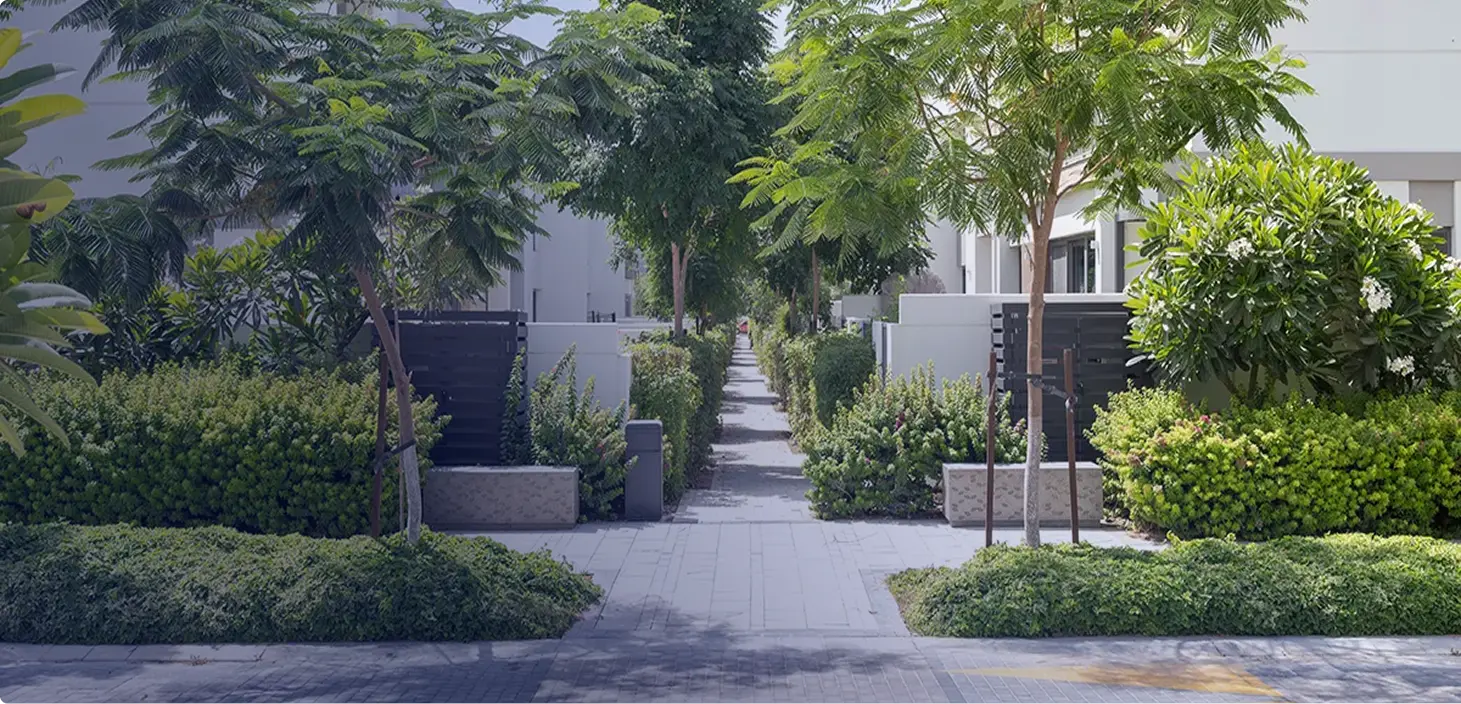
The developments that hold their value and retain residents will not be the ones with the best renders or marketing. They will be the ones where three decisions were made well before the master plan was fixed, and at the pace this market has built, too few were.
Emaar ended 2025 with a revenue backlog of AED 155 billion, up 39% year on year. Aldar closed the same year with AED 61 billion of development backlog in the UAE, part of a record group total of AED 71.7 billion. Emaar Development alone reports around 51,000 residential units under development and waiting to be handed over.
Dubai is heading for its highest annual residential completions since 2008, with around 55,600 units expected in 2026 and more than 60,000 forecast for 2027. Only around a third of the roughly 525,000 units scheduled for delivery through 2030 have passed early construction progress, which means the wave keeps building for years, and what gets designed into those developments today decides whether they are ready for it.
Behind every one of those units is a community promise: a lifestyle, a public realm, a managed environment, a quality of daily life that was used to justify the price. The question many developers are only now starting to answer is whether the operational layer they are handing over can keep it.
What happens in the space
Most public realm is designed for how it looks before anyone decides how it will be used. The activation question, what should happen in these spaces, for whom, and how that is sustained over time, tends to be answered last, usually after handover and usually in response to a problem.
That sequence is expensive. Activation programmed to fill a calendar, rather than to serve a specific community need, fades once the launch marketing budget moves on, and the community centre sits empty because it was sized and fitted for a general resident who does not exist rather than for the households who actually live there.
The activation brief has to come from the same place as the experience brief: the people who will live in the development, what they need from their shared environment, and what will make them want to stay. Asked early, that question determines what gets programmed, who gets the brief, and what the community management operation needs to sustain. It also determines which spaces can generate revenue and which are purely experiential, a distinction that matters significantly for the financial model.
What the operational layer needs to be
Operational space is usually sized by convention: rule of thumb ratios, facilities management (FM) norms and default benchmark assumptions. The underlying assumption is that public realm area drives operational requirement, which makes area a weak proxy for what a place actually needs.
The variables that determine how much operational infrastructure a development needs are the nature of the assets being maintained, the experience the development has promised to deliver, and the resident and user profiles that generate demand. A high-density urban development with a luxury promise, active programming and a mixed user base needs very different provision from a suburban residential scheme of equivalent land area. Neither the area nor the unit count tells you that. Understanding what the development has promised its residents, and what their daily lives will require, does.
Getting this decision right requires a cross-portfolio view. Applied across one major Abu Dhabi master developer’s portfolio of 12 projects, this approach identified a 42% reduction in operational gross floor area (GFA) and AED 252 million in construction cost savings through cross-portfolio efficiency analysis. Neither figure was visible from a single-project perspective, and both came from asking what the experience actually required.
Governance sits within the same decision. The strata framework determines how the operational layer is managed, funded and held to account once the developer steps back. Dubai’s Law No. 6 of 2019 gives the Real Estate Regulatory Agency (RERA) approval over service charges and management budgets, and in March 2025 the Dubai Land Department (DLD) launched the Tayseer initiative with the stated aim of reducing the number of service fee cases reaching the Rental Disputes Centre. A strata framework drafted only for legal compliance satisfies registration requirements and leaves funding and accountability open to dispute. Those disputes are the predictable outcome of strata treated as a legal formality instead of a community design decision.
A strata framework designed to support the experience promise, with governance principles that reflect how the community is intended to function, produces a structure that carries the development’s brand beyond handover.
How it gets resourced and what it returns
The sourcing decision looks commercial. Its consequences are experiential first and commercial second.
When facilities management and community management (CM) are procured on price, through competitive tender against a service level agreement (SLA), the contract is built to control cost. The experience the development promised sits outside its terms, so service quality drifts, the developer’s brand absorbs the damage, and residents who have a choice use it.
Developers who specify FM and CM against an experience brief, defining what residents should experience before deciding what they are willing to pay, procure differently, manage differently and retain differently. The service charge becomes a justified cost rather than a complaint, and the brand equity holds.
Ownership decisions sit in the same territory. Which operational assets does the developer retain? Which transfer to authorities, third parties or community associations? Which are shared across asset classes within the development? Most of these decisions are made implicitly, by convention, by regulatory default, or because no one asked the question at the right moment. By the time handover arrives, the retention and transfer structure is fixed, while the financial consequences keep running.
Revenue from operational assets is the other side of the same question. Most developers treat public realm operational assets as cost centres by default, and that default is a choice. Assets designed for revenue from the outset, where programming, tenanting and service monetisation are part of the brief, contribute to the financial model instead of drawing from it. In a market where off-plan sales made up 72% of Dubai residential transactions in the first quarter of 2026, the service model and community experience are often the clearest differentiator between comparable products. The developer who has modelled that revenue, and built the operational layer to capture it, holds a different asset from the one who assumed it.
None of that comes from cutting cost. It comes from asking the right questions before the master plan is fixed.
Public realm is one of the largest cost lines on any master development. Done properly, it is also one of the strongest reasons people stay.
- Emaar Properties, full year 2025 results, February 2026
- Emaar Development, dividend announcement and company profile, March 2026
- Aldar Properties, Q4 and full year 2025 financial results, February 2026
- Khaleej Times, Dubai set for highest annual home deliveries since 2008 as new launches slow, August 2026
- Global Property Guide, UAE residential property market analysis 2026, drawing on Property Monitor, Cavendish Maxwell and Savills data
- Dubai Legislation Portal, Law No. 6 of 2019 concerning ownership of jointly owned real property
- Dubai Land Department, Tayseer initiative launch, March 2025
Public realm is one of the largest cost lines on any master development. Done properly, it is also one of the strongest reasons people stay.
If you want to understand how these frameworks apply to your portfolio
Contact usDownload this quote
The selected quote appears here.